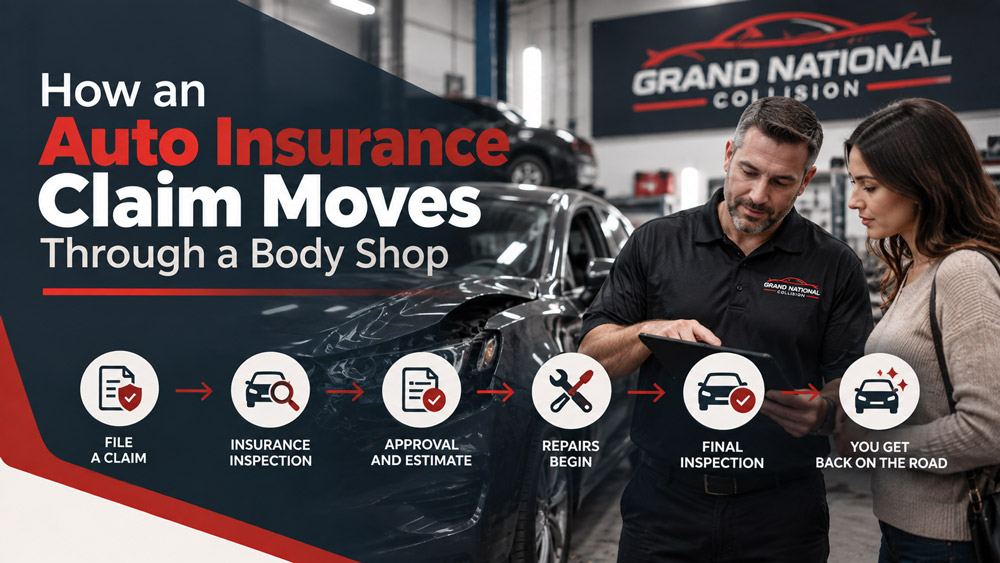
What happens between filing a claim, getting a first estimate, and picking up the finished repair.
An auto insurance claim and an auto repair are related but separate processes, and understanding how they fit together removes a lot of the uncertainty people feel after a collision. The insurer decides what is covered under the policy; the body shop determines what the vehicle actually needs and performs the work. Most of the friction in a claim comes from the gap between those two roles.
The claim usually begins with a report to the insurer. You provide the policy number, the date and location of the incident, the other driver information, and any police report number. The insurer may ask you to submit photos or to bring the vehicle to a location for an inspection. Ask specifically whether it wants to inspect the vehicle before any repair begins, because starting work first can complicate the process.
Next comes the first estimate. This estimate is based on the damage that is visible when the vehicle is examined. In collision repair, that is a starting point, not a final number. Modern vehicles hide a great deal behind bumper covers, trim panels, and wheel wells, and damage that is obvious once the vehicle is apart can be invisible during an initial walkaround.
That is where the supplement comes in. A supplement is additional work, found after disassembly or during the repair, that was not in the original estimate. The shop documents it, often with photos and measurements, and submits it to the insurer for approval. A supplement is a normal part of collision repair, not a sign that the first estimate was dishonest. It reflects the difference between what can be seen and what is actually there.
Approval and authorization are the insurer decisions. The insurer reviews the estimate and any supplement against the policy and authorizes the covered work. Deductibles, coverage limits, rental car benefits, and whether the policy pays for original equipment or aftermarket parts are all determined by the policy terms, not by the shop. Questions about coverage belong with the insurer; questions about the repair belong with the shop.
While the vehicle is being repaired, the shop orders parts, performs the structural and body work, refinishes panels, and reassembles the vehicle. Parts availability is one of the biggest variables in timing, especially for late-model vehicles or uncommon trim levels. Paint work also adds time because the finish has to be mixed, applied, and allowed to cure between stages.
The final step is the invoice and the return of the vehicle. The invoice documents the approved work and the parts and labor used. Before you settle the claim, review the repair in daylight. Check that panels align, that doors and the hood close cleanly, and that lamps and trim sit flush. If something looks off, raise it before you close out the claim, because it is easier to correct while the file is still open.
One decision customers often ask about is where to have the repair done. Many policies allow you to choose the shop, while some insurers steer work to a partner network. The two arrangements can differ in how the claim is handled, but the repair still has to be documented the same way. If you are unsure what your policy allows, ask the insurer directly, then confirm with the shop that it accepts the arrangement. Knowing that answer before work starts avoids a disagreement later.
None of this is legal or financial advice, and no website can interpret your specific policy. The useful takeaway is simpler: know the stages, ask who approves what, and keep your paperwork together. If you understand that the first estimate is a starting point and that a supplement is routine, the process becomes far less confusing, and you can focus on getting a safe, well-repaired vehicle back on the road.